Check your Flat Rate Scheme rate.
On the Flat Rate Scheme your percentage depends on whether you are a limited cost business: one whose spend on goods in a return period is under 2% of its VAT-inclusive turnover, or under £1,000 a year (£250 for a quarter), whichever is greater. The app works this out on every Flat Rate return and shows it. It never changes your rate and never stops you filing.
- Open Records, then Categories, and choose the Expenses section.
- Press Edit on each expense category that holds goods you buy to sell on or use up, and tick Counts as goods for the limited cost test. Leave it unticked for services, vehicles, fuel, and food and drink for staff.
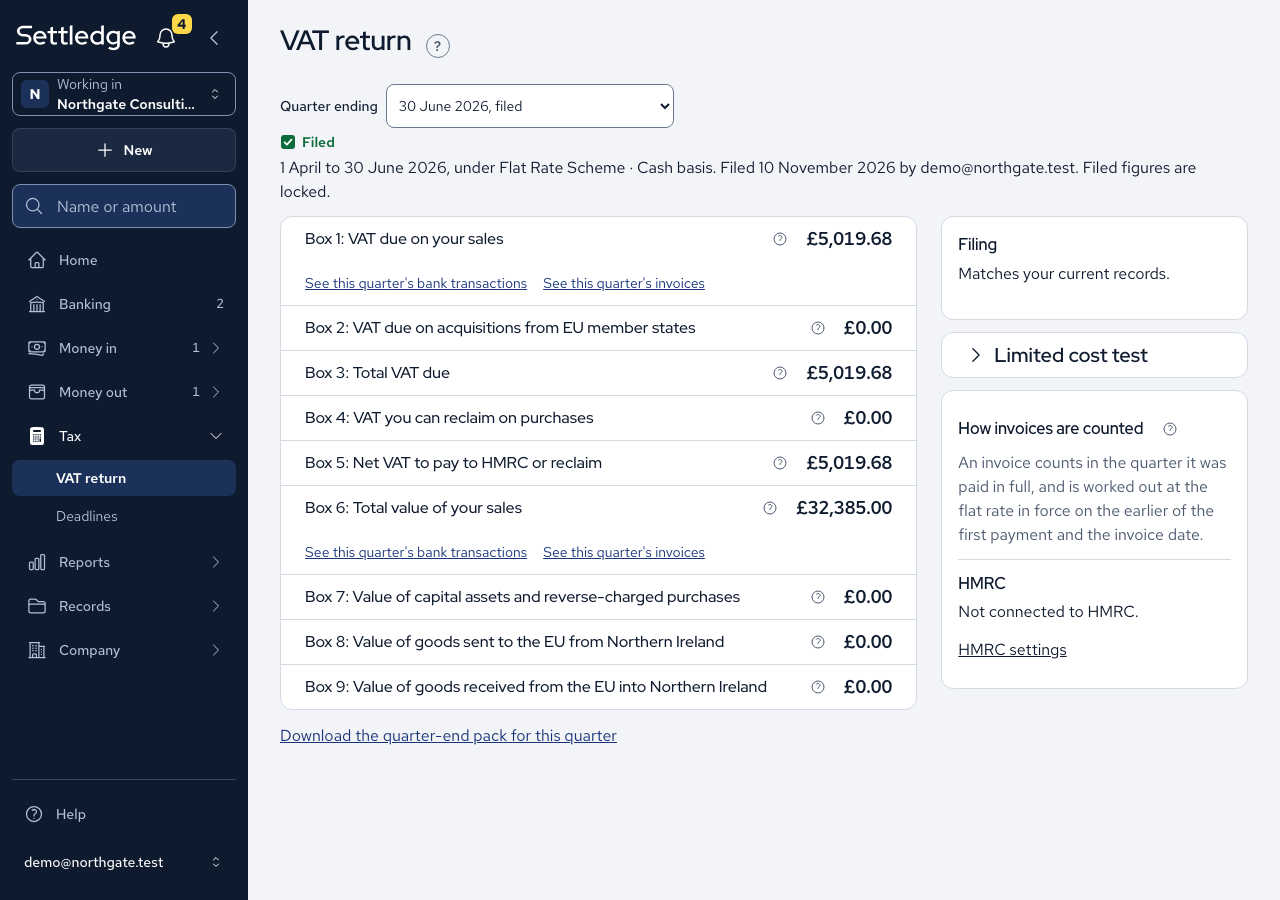
- Open Tax, then VAT return, and choose a quarter. Below the nine boxes, the Limited cost test section lists Goods spend (VAT included), Turnover (Box 6), Threshold, Flat Rate percentage recorded and Limited cost?, with the working under Threshold.
- Read the sentence under the rows. If it says your goods spend is under the threshold, the limited cost rate applies, so check the percentage recorded above is that rate. If it says it is not, the full rate applies.
- If the rate on record is wrong, follow VAT rate screen. It opens Flat rate in Settings. Under Add a rate, enter the right Flat rate percentage, set Effective from to the first day of that quarter and press Add rate. The link appears only if you may change rates and no filed return would change.
Cases
- The comparison is strict: spend equal to the threshold is not under it. The exact 2% figure is compared, not the rounded one shown.
- Each return is tested on its own figures, and a quarter in progress is headed "So far this quarter" with the note "This can change until the quarter ends."
- On a filed return the test is worked out from your records today and the panel says it is not part of the filed figures.
- Capital assets are never counted as goods.
- A bank line with no category stops the test: "This test cannot be worked out until 1 transaction in this quarter is categorised."
- The panel counts the expense categories you have not marked, for example "16 expense categories are not marked as goods, so their spend is not counted."
- A company on the Standard Scheme has no limited-cost test.
Good practice
- Mark your goods categories once, before the first return, so the spend is not understated.
- Check the test every quarter. Your answer can change from one return to the next.